Best REITs to Invest In 2026: Top Real Estate Investment Trusts to Consider
Investing in real estate does not always require purchasing a house, apartment, or commercial property. Real Estate Investment Trusts (REITs) allow investors to gain…

A non-qualified retirement plan can offer another way to save for retirement by allowing eligible employees to defer compensation or receive additional retirement benefits from their employers. These arrangements are often used by executives, highly compensated employees, and certain key employees.
Unlike qualified retirement plans, non-qualified plans do not have to satisfy all the same IRS qualification requirements. However, they must follow specific tax rules, particularly when compensation is deferred under Section 409A of the Internal Revenue Code.
In this guide, you will learn what a non-qualified retirement plan is, how it works, its different types, tax implications, advantages, disadvantages, and how it compares with a qualified retirement plan.
A non-qualified retirement plan is an employer-sponsored compensation arrangement that provides retirement benefits or allows employees to receive compensation at a future date.
These plans are commonly designed for executives, senior managers, and other selected employees who want additional retirement benefits beyond the limits or structure of traditional qualified retirement plans.
A non-qualified deferred compensation plan may allow an employee to postpone receiving a portion of their salary, bonus, or other eligible compensation until retirement or another permitted payment event.
Unlike a traditional 401(k), a typical non-qualified deferred compensation arrangement does not receive the same tax-qualified status under Section 401(a).
The employer and employee generally agree on the amount of compensation to defer, the conditions for receiving benefits, and the payment schedule.
A non-qualified retirement plan generally works through an agreement between an employer and an eligible employee.
The employer establishes the plan and determines who can participate. Depending on the arrangement, employees may defer part of their compensation, or the employer may promise to provide additional retirement benefits.
Here is how the process typically works:
The payment terms must be established and administered according to the applicable tax rules. Section 409A generally restricts when deferred compensation can be paid and when employees can change their payment elections.
There are several types of non-qualified retirement arrangements. Each has a different purpose and may be designed to address specific compensation or retirement planning needs.
A non-qualified deferred compensation plan allows eligible employees to delay receiving part of their compensation until a future date.
For example, an executive may choose to defer a portion of their annual bonus and receive it after retirement.
Depending on the plan’s terms and applicable tax rules, the deferred compensation may accumulate with interest or hypothetical investment returns.
A Supplemental Executive Retirement Plan, commonly called a SERP, provides additional retirement benefits to selected executives.
Employers often use SERPs to reward senior employees, encourage long-term employment, and supplement retirement benefits available through qualified plans.
A SERP may promise a specified retirement benefit based on factors such as salary, years of service, or a predetermined formula.
An excess benefit plan is designed to provide additional retirement benefits to employees whose benefits under a qualified retirement plan are limited by certain federal tax restrictions.
For example, an executive with a high salary may not receive retirement benefits proportionate to their compensation under a qualified plan because of applicable IRS limits.
An excess benefit arrangement may provide additional benefits to address that difference.
A salary continuation plan is an arrangement under which an employer promises to pay an employee a specified amount of compensation after retirement or another qualifying event.
Payments may be structured as installments over several years or according to another agreed schedule.
These plans can provide additional retirement income, but their tax treatment depends on the specific arrangement.
Certain tax-exempt organizations and governmental employers may offer arrangements under Section 457(f).
These plans are generally known as ineligible deferred compensation plans. They can allow eligible employees to defer compensation under specific conditions, often involving a substantial risk of forfeiture.
When the applicable forfeiture risk ends, the deferred compensation generally becomes taxable under Section 457(f), subject to the applicable rules.
Important: Not every non-qualified retirement plan is a 457(f) plan. Different rules apply depending on the employer, plan structure, and type of deferred compensation.
The main difference between qualified and non-qualified retirement plans is how they are structured and the federal requirements they must satisfy.
Qualified plans generally meet the requirements of Section 401(a) or other applicable tax provisions. Non-qualified plans do not receive the same qualified status.
| Feature | Qualified Retirement Plan | Non-Qualified Retirement Plan |
|---|---|---|
| IRS qualification | Must meet applicable qualification rules | Does not receive qualified plan status |
| Participation | Often available to a broader employee group | Frequently limited to selected employees |
| Contribution limits | Subject to applicable federal limits | Generally not subject to the same qualified-plan contribution limits |
| Tax treatment | Often provides tax-deferred contributions and growth | Depends on the arrangement and applicable tax rules |
| Employer funding | Often held in a qualified plan trust | May remain an employer obligation |
| Creditor protection | Generally receives specific legal protections | May expose participants to employer-creditor risk |
| Common examples | 401(k), traditional pension, 403(b) | SERP and non-qualified deferred compensation |
A non-qualified plan can supplement a qualified retirement plan, but it generally does not replace the protections and tax treatment associated with qualified plans.
Tax treatment is one of the most important considerations when evaluating a non-qualified retirement plan.
Unlike traditional 401(k) contributions, which generally receive tax-deferred treatment under qualified plan rules, non-qualified deferred compensation follows different rules.
In a properly structured non-qualified deferred compensation arrangement, employees generally recognize income when the compensation is paid or otherwise becomes taxable under the applicable rules.
However, Section 409A contains strict requirements. If a plan fails to comply with these rules, affected deferred compensation may become immediately taxable to the employee to the extent it is no longer subject to a substantial risk of forfeiture and has not already been included in income.
A Section 409A violation can create significant tax consequences.
Affected compensation may become subject to:
This makes proper plan design, payment scheduling, and administration especially important.
Employers generally cannot deduct non-qualified deferred compensation merely when it is promised or deferred.
For many arrangements, the employer’s deduction generally occurs when the employee or service provider recognizes the compensation as income, subject to applicable tax rules.
Federal employment tax treatment can differ from income tax treatment. Certain deferred compensation amounts may become subject to Social Security and Medicare taxes at an earlier point than when they are included in income for federal income tax purposes.
Employers should review the applicable payroll tax rules when administering these arrangements.
Non-qualified retirement plans can provide benefits to both employers and eligible employees.
Employees may have an opportunity to defer additional compensation beyond the contribution limits that apply to certain qualified retirement plans.
This can be especially useful for executives who want to build additional retirement income.
Employers can design certain non-qualified plans around the compensation and retention goals of their organization.
Payment schedules and benefit structures may be customized within applicable legal and tax requirements.
Companies can use long-term deferred compensation arrangements to encourage key employees to remain with the organization.
Benefits may depend on continued employment or meeting specific performance conditions.
A non-qualified plan can provide retirement benefits in addition to Social Security, personal savings, and qualified retirement accounts.
This may help eligible employees create a more comprehensive retirement income strategy.
Offering additional retirement compensation may help companies attract experienced executives and highly skilled employees.
Although non-qualified retirement plans offer flexibility, they also have important disadvantages.
One of the biggest risks is that deferred compensation may remain an unsecured obligation of the employer.
If the employer experiences financial difficulties or bankruptcy, participants may have to compete with the employer’s general creditors to recover promised benefits.
Some plans use a rabbi trust, but assets in a typical rabbi trust generally remain available to the employer’s general creditors.
Many non-qualified plans are designed for selected management employees or highly compensated individuals.
Regular employees may not qualify to participate.
Non-qualified deferred compensation arrangements can involve complicated tax requirements, including Section 409A, payroll tax rules, and special provisions for tax-exempt employers.
Improper administration can create unexpected tax liabilities.
Employees generally cannot withdraw deferred compensation whenever they want.
Payments must follow the plan’s terms and applicable tax rules. Early access may be restricted to specific permitted events.
Some plans provide hypothetical investment returns rather than actual ownership of investment assets. The value of benefits may depend on the employer’s promises and the plan’s financial terms.
Employees should understand how benefits are calculated and whether any return is guaranteed.
Non-qualified retirement plans may be useful for certain employees and employers.
Executives and senior managers: These employees may want additional retirement benefits beyond those available through qualified plans.
Highly compensated employees: Individuals with higher incomes may use deferred compensation arrangements as part of a broader financial strategy.
Business owners: Certain business owners may explore non-qualified arrangements for executive compensation or retention, subject to applicable legal requirements.
Employers: Companies may use these plans to attract, reward, and retain key employees.
However, these arrangements are not suitable for everyone. Participants should evaluate employer financial strength, payment terms, tax consequences, and the possibility of losing deferred benefits.
Leaving an employer does not automatically mean that all deferred compensation becomes payable immediately.
The payment depends on the plan document and the applicable tax rules.
Common payment events may include:
Section 409A generally requires distributions to follow the payment events and schedules established under the plan.
Some specified employees of publicly traded companies may also be subject to a six-month delay before certain separation-from-service payments can be made.
Before leaving a job, employees should review their deferred compensation agreement to understand when benefits become payable and what tax consequences may apply.
The main purpose is to provide additional retirement or deferred compensation benefits to selected employees beyond those available through qualified retirement plans.
Tax treatment depends on the arrangement. Properly structured deferred compensation is generally taxed when paid or otherwise includible in income under applicable rules. A Section 409A violation can cause earlier taxation and additional federal taxes.
Neither option is automatically better. A 401(k) generally offers qualified-plan protections and tax advantages, while a non-qualified plan may provide additional compensation opportunities for selected employees. The right option depends on individual circumstances and employer financial strength.
Withdrawals are generally restricted by the plan’s terms and applicable tax rules. Section 409A permits payments only upon certain specified events or according to an established payment schedule.
Not necessarily. Many non-qualified deferred compensation plans are unfunded arrangements, meaning the deferred amounts remain an obligation of the employer and may be exposed to employer creditors.
Participation depends on the type of plan and applicable legal requirements. Many employer-sponsored arrangements are designed for executives, senior managers, and highly compensated employees.
A SERP is a type of non-qualified executive retirement arrangement that promises supplemental retirement benefits. A non-qualified deferred compensation plan more broadly allows eligible employees to postpone receiving compensation until a future date.
A non-qualified retirement plan can be a useful part of an executive’s long-term financial strategy. It may provide additional retirement income, flexible compensation arrangements, and benefits beyond those offered by traditional qualified retirement plans.
However, these plans also involve important considerations, including employer credit risk, limited access to funds, and complex tax rules under Section 409A.
Before participating in a non-qualified retirement plan, review the plan documents, understand the payment schedule, evaluate the employer’s financial position, and consider speaking with a qualified tax or financial professional.
A well-designed arrangement can support long-term retirement goals, but understanding its risks is essential before deferring compensation.
Bonus Tax Aggregate Calculator
Dual Scenario Hourly Calculator
Dual Scenario Salary Calculator
Standard vs. Itemized Deductions: Which Is Better for Your 2026 Taxes?
Investing in real estate does not always require purchasing a house, apartment, or commercial property. Real Estate Investment Trusts (REITs) allow investors to gain…
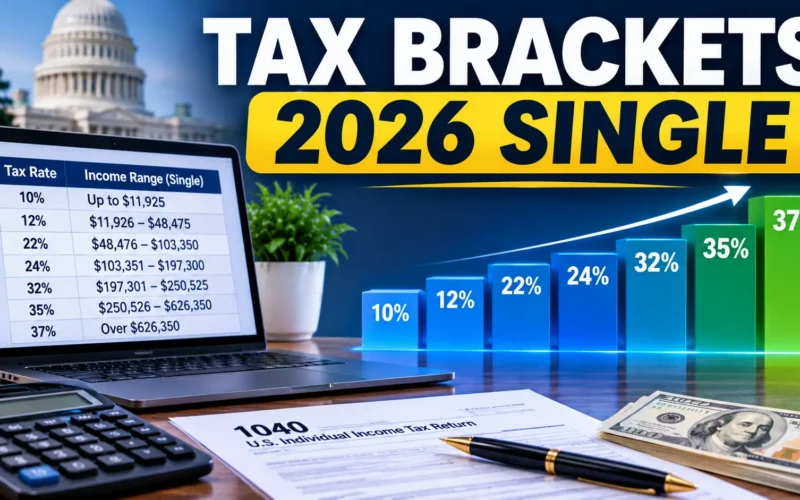
Understanding the 2026 tax brackets for single filers can help you estimate your federal income tax, plan your finances, and avoid surprises when filing…
Saving for retirement becomes especially important as workers approach their 60s. For people who have not accumulated enough retirement savings, making additional contributions to…